
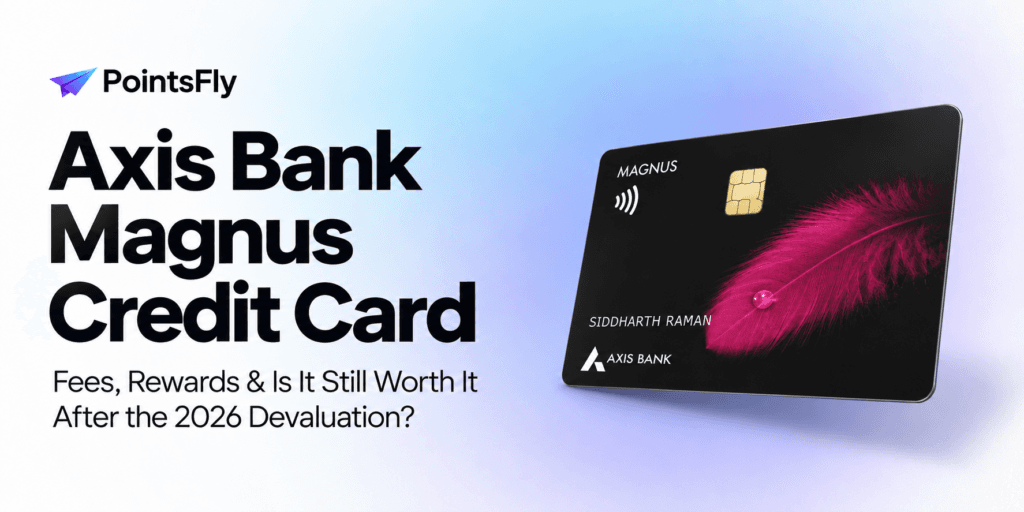
If you’ve landed on this page, one of two things is probably going on. Either you’re staring at a ₹12,500 joining fee and trying to decide if the Axis Bank Magnus Credit Card is worth it, or you got a notice about “updated terms and conditions” and you’re trying to figure out what just got taken away. We built this page for both of you.
This Axis Bank Magnus Credit Card review breaks down every fee, the real EDGE Rewards earning rate, every devaluation Axis has pushed through since 2023 (including the one that just landed in August 2026), and an honest read on whether the ₹12,500 fee still makes sense for you.
Here’s the gap that matters: redeem your EDGE Reward Points through the catalogue and you’re looking at roughly ₹0.20–₹0.25 per point. Transfer the same points to an airline or hotel partner instead, and a well-timed transfer can be worth several times that. On a Travel EDGE spend of ₹1.5 lakh in a month, that’s the difference between a ₹10,000 voucher and miles worth two to three times more.
 Quick Answer
What Is the Axis Bank Magnus Credit Card?
The Axis Bank Magnus Credit Card is a premium travel and rewards card built for high spenders. It earns EDGE Reward Points on every eligible transaction, which convert into cashback, vouchers, merchandise, or transfers to 20+ airline and hotel loyalty programmes.
Think of it as Axis’s flagship travel card, built for customers who spend well above ₹1.5 lakh a month and want that spend to turn into flights and hotel stays rather than statement credit.
The real value lies in how you redeem your EDGE points, not how many you’ve earned, and that’s exactly the part this review focuses on.
Key Takeaways

Magnus earns 12 EDGE points per ₹200 (6 per ₹100), and 60 per ₹200 through Travel EDGE, a real 5X.

The ₹12,500 annual fee waives only if you spend ₹25 lakh a year, a bar Axis raised in 2023.

Catalogue redemptions pay ₹0.20–₹0.25 per point; airline transfers can be worth several times more.

Axis has devalued this card three times since 2023, most recently on 28 August 2026.
Table of Contents
- How You Earn EDGE Points on Axis Magnus
- What Your EDGE Points Are Actually Worth
- What Changed: The 2026 Devaluation, Explained
- Airport Lounge & Travel Benefits
- Fees & Charges
- How Axis Magnus Compares
- Who Should (and Shouldn’t) Get This Card
- Eligibility & How to Apply
- Real Redemption Walkthrough
- FAQs
How You Earn EDGE Points on Axis Magnus
Every rewards card runs on a simple loop:
Spend on your Magnus card → EDGE Points credited to your account → Redeem via the catalogue or transfer to 20+ airline and hotel partners
You earn 12 EDGE Points per ₹200 (6 per ₹100) on regular spends up to ₹1.5 lakh in a month, and 35 EDGE Points per ₹200 (17.5 per ₹100) on the portion of monthly retail spend above that. Book through the Travel EDGE portal and the rate jumps to 60 points per ₹200 (30 per ₹100), capped at ₹2 lakh a month, a real 5X over the base rate.
What doesn’t earn points at all: wallet loads, EMI conversions, fuel, insurance, gold and jewellery, utilities, government payments, and, as of the August 2026 update, gift card purchases and toll/road/bridge fee transactions.
When Points Actually Land
Base EDGE Points usually show up within about 15 days of the transaction. Points earned at an accelerated rate (Travel EDGE, or the ₹1.5 lakh+ monthly bonus) take longer, typically around 45 days, since Axis runs a separate validation pass on those. Quick gut check on the base rate: ₹20,000 in regular spend earns 1,200 EDGE Points (₹20,000 ÷ ₹200 × 12).
Earning Rate Is Only Half the Story, Here’s Why…
A high earning rate feels good, but it’s only step one. Two people can earn the exact same number of points and end up with wildly different outcomes, because what happens after you earn them is where most of the value gets won or lost. That’s the part this guide focuses on.
What Your EDGE Points Are Actually Worth
This is the table that matters more than your points balance itself:
| Redemption Type | Typical Value per Point | Effort Required |
|---|---|---|
| Cashback / statement credit | ₹0.20–₹0.25 | Lowest |
| Gift vouchers (Amazon, Flipkart, etc.) | ₹0.15–₹0.25 | Lowest |
| Merchandise catalogue | ₹0.10–₹0.20 | Lowest |
| Hotel transfer/booking | ₹1.00–₹2.00 | Moderate |
| Airline transfer | ₹2.50–₹3.00+ | Moderate |
| Premium cabin / peak-season redemption | ₹4.00–₹5.00 | Highest, requires planning |
Person A vs. Person B: Same 45,000 Points, Very Different Outcomes
Say you spend ₹1.5 lakh in a month, entirely through the Travel EDGE portal (booking flights and hotels directly through it). That’s 45,000 EDGE Points.
- Person A redeems all 45,000 points through the EDGE catalogue for gift vouchers. At roughly ₹0.20–₹0.25 per point, that’s about ₹9,000–₹11,250, a modest, guaranteed return.
Where Your EDGE Points Can Actually Go
You’ve seen that catalogue redemptions cap out around ₹0.20–₹0.25 a point. Here’s the other half: who you can actually transfer to, and at what rate. Most partners run at 5 EDGE Points = 2 miles/points. A smaller group runs at 5:1.
Airline Partners (5 EDGE Points = 2 Miles)
| Airline | Programme |
|---|---|
| Air Canada | Aeroplan |
| Ethiopian Airlines | ShebaMiles |
| Etihad Airways | Etihad Guest |
| Japan Airlines | JAL Mileage Bank |
| Singapore Airlines | KrisFlyer |
| Thai Airways | Royal Orchid Plus |
| Turkish Airlines | Miles&Smiles |
| United Airlines | MileagePlus |
| AirAsia | AirAsia Rewards |
| Air France-KLM | Flying Blue |
| Air India | Maharaja Club |
| Qantas Airways |
What Changed: The 2026 Devaluation, Explained
If you’re searching for this specifically because Axis emailed you about “updated terms,” here’s the honest timeline. Magnus has been revised three times in three years, and each round has traded away a little more of the card’s original value.
September 2023
Reward structure moved from a flat rate to spend-based tiers. Transfer ratio was cut from 5:4 to 5:2 with a new 5-lakh-point annual cap. The ₹1 lakh spend milestone bonus (25,000 points) was removed entirely. Annual fee rose from ₹10,000 to ₹12,500, and the waiver threshold jumped from ₹15 lakh to ₹25 lakh.
April 2024
More categories were excluded from earning (insurance, fuel, gold & jewellery). Transfer partners were split into capped groups (1 lakh points/year for Group A, 4 lakh for Group B). Domestic lounge access turned spend-conditional (₹50,000 in the previous 3 months) instead of unlimited, guest lounge visits were halved from 8 to 4 a year, and concierge and airport meet-and-assist services were discontinued.
August 2026
Gift card purchases and toll/road/bridge fee transactions no longer earn points. Forex markup was raised from 1.5% to 2%. Priority Pass is no longer accepted for domestic lounge access (international access is unaffected), and the late payment fee was revised to ₹1,300 on balances above ₹50,000.
Is it still worth ₹12,500? If you’re spending well above ₹1.5 lakh a month, booking travel through Travel EDGE, and actually transferring points to airline or hotel partners, yes, the earn rate and lounge access still outperform most of the market. If you’re using this as a general spending card and redeeming through the catalogue, the fee has gotten harder to justify with every revision since 2023.
Airport Lounge & Travel Benefits
Beyond the points, this is where a lot of Magnus’s real-world value sits, provided you actually travel enough to use it.
International Lounges
Unlimited complimentary visits for the primary cardholder via Priority Pass, plus 4 complimentary international guest visits a year.
Domestic Lounges
Unlimited visits at select Indian airports, but only if you’ve spent ₹50,000 in the previous 3 months (waived for the first 3 months on a new card). Since August 2026, this runs through Axis’s own domestic lounge programme rather than Priority Pass.
Other Travel & Dining Perks
Discounts at 4,000+ restaurants across India through Dining Delights, 15% off bed-and-breakfast rates at The Leela Palace Hotels & Resorts (valid till 30 September 2026; check if it’s been renewed by the time you’re reading this), and periodic travel booking offers through Goibibo, MakeMyTrip and similar partners. These coupon-based offers change often, so treat any specific code you see elsewhere as expired until you’ve confirmed it on Axis’s live offers page.
Current Merchant Offers on Axis Magnus
Beyond travel and lounges, Magnus runs a rotating set of merchant discounts. Codes and windows change often, so treat this as accurate as of mid-September 2026 and confirm on Axis’s live offers page before you swipe. (A few offers from earlier this year, including a Goibibo and an earlier MakeMyTrip festival code, have already lapsed and aren’t listed here.)
Travel
| Offer | Discount | Code | Valid Till |
|---|---|---|---|
| MakeMyTrip (International, Wednesdays) | Up to 20% off, max ₹20,000 | MMTAXISBIZ | 30 Sep 2026 |
| Air India | ₹3,000 off | — | 15 Oct 2026 |
| Cathay Pacific | Up to ₹10,000 off | — | 31 Dec 2026 |
| Musafir | Up to ₹1,500 off | MUADHDDF | 15 Oct 2026 |
| FabHotels | 25% off | FABADN10 | 15 Oct 2026 |
Electronics
Fees & Charges
Joining & Annual Fee
The joining and annual fee are identical: ₹12,500 + applicable taxes each year. That fee is waived only if you spend ₹25 lakh in the preceding year, up from ₹15 lakh before the September 2023 revision, so the bar to get this card “free” has gotten noticeably higher.
Forex Markup & Cash Withdrawal
Foreign currency markup is 2%, raised from 1.5% in the August 2026 revision, a real cost increase if you spend abroad often. Cash withdrawal carries no fee, but interest charges apply from the day of withdrawal, so treat this as “no fee, not free money.”
Fuel Surcharge & Late Payment Fee
Fuel surcharge is waived at 1% on transactions between ₹400–₹4,000, capped at ₹400/month. Late payment fee was revised in August 2026 to ₹1,300 on outstanding balances above ₹50,000; check your statement due dates closely if you carry a higher balance. None of these are unusual for a card in this segment, but the forex markup increase and the tougher fee-waiver threshold are the two changes that quietly raise your real cost of holding this card year over year.
Insurance & Protection Benefits
Magnus also bundles a few protection covers most cardholders never end up filing a claim on, but are worth knowing exist.
| Benefit | Coverage |
|---|---|
| Credit Shield | Up to ₹5,00,000 |
| Purchase Protection | Up to ₹2,00,000 |
| Baggage & personal document protection (loss/delay of baggage, loss of documents) | Up to USD 500 |
These are protection benefits, not automatic payouts. Actual claims are subject to Axis’s insurance terms and exclusions, worth a read before you assume you’re covered.
How the Axis Bank Magnus Credit Card Compares
Points across these three programmes aren’t directly comparable: an EDGE Point earned on the Axis Bank Magnus Credit Card, an HDFC Reward Point and a Diners Club Rewards Point each carry different transfer value depending on where you send them. But the fee-waiver gap is real and worth sitting with:
| Axis Magnus | HDFC Infinia | HDFC Diners Club Black | |
|---|---|---|---|
| Joining/Annual fee | ₹12,500 + taxes | ₹12,500 + taxes | ₹10,000 + taxes |
| Fee waiver spend | ₹25 lakh | ₹10 lakh | ₹8 lakh |
| Welcome benefit | ₹12,500 voucher | 12,500 bonus points | Marriott/Prime/Swiggy memberships on ₹1.5L spend in 90 days |
| Base earn rate | 12 pts/₹200 (6/₹100) | 5 pts/₹150 (~3.3/₹100) | 5 pts/₹150 (~3.3/₹100) |
| International lounge | Unlimited (primary) + 4 guest visits/yr | Unlimited (primary + add-on) | Unlimited (primary + add-on) |
| Domestic lounge | Unlimited, if ₹50k spent in last 3 months |
Who Should (and Shouldn’t) Get This Card
Get it if:
• You consistently spend more than ₹1.5 lakh a month on eligible categories
• You book flights and hotels through Travel EDGE rather than directly with airlines/OTAs
• You’re comfortable transferring points to airline or hotel programmes instead of redeeming for cashback or vouchers
• You travel internationally often enough to make unlimited Priority Pass access genuinely useful
• You can realistically hit ₹25 lakh in annual spend to waive the fee, or you’ve decided the benefits are worth paying for outright
Think twice if:
• Most of your spending falls in excluded categories: fuel, utilities, insurance, gold, EMIs
• You redeem points for cashback or vouchers rather than transferring them (you’ll be earning a premium card’s fee for a mid-tier card’s real return)
• You rarely fly internationally, since the international lounge benefit is where a lot of this card’s value sits
• You’re not able to track which of your transactions are actually earning points, given how long the exclusion list has gotten
Axis Bank Magnus Credit Card: Eligibility & How to Apply
The Axis Bank Magnus Credit Card is open to salaried and self-employed applicants aged 18–70, with a stated minimum annual income of ₹24 lakh. Final approval depends on your income documentation, credit history and Axis’s internal underwriting; there’s no fixed credit score cutoff published. You can apply directly through Axis Bank’s website or a branch; have your income proof, PAN and KYC documents ready before you start.
Real Redemption Walkthrough
Here’s where this gets practical. Say you run ₹2 lakh a month through Travel EDGE for six months while planning a family trip abroad. At 60 points per ₹200 (capped at the ₹2 lakh monthly threshold), that’s 60,000 EDGE Points a month: 3,60,000 over six months.
The question isn’t “how many points do I have.” It’s “what did each rupee I spent actually earn, after exclusions, and when should I transfer to get the most out of a partner programme’s periodic bonus.” That’s the part almost no one tracks manually, and it’s the exact gap PointsFly’s AIRA is built to close: it watches your transactions against each card’s actual earning rules (including new exclusions like the ones Axis added in August 2026), tells you what you’ve really earned instead of what you assume you’ve earned, and flags when a transfer partner is running a bonus worth timing your redemption around.
Not Sure What Your Axis Magnus EDGE Points Are Actually Worth?
Try out our free Reward Points Calculator and see what your EDGE Points are really worth before you redeem them.
FAQs
About the Author
Vibhav Singh is the Founder & CEO of PointsFly and a credit card rewards strategist with 35,000+ Instagram followers (@pointsflywithvibhav). He has personally booked 200+ flights on points and previously built XTEN-AV, an AI-powered SaaS platform now used in 130+ countries.

