
Know Your Cards18 min read
Checked against HDFC Bank’s card pages, reward terms and fee schedules, October 2026.
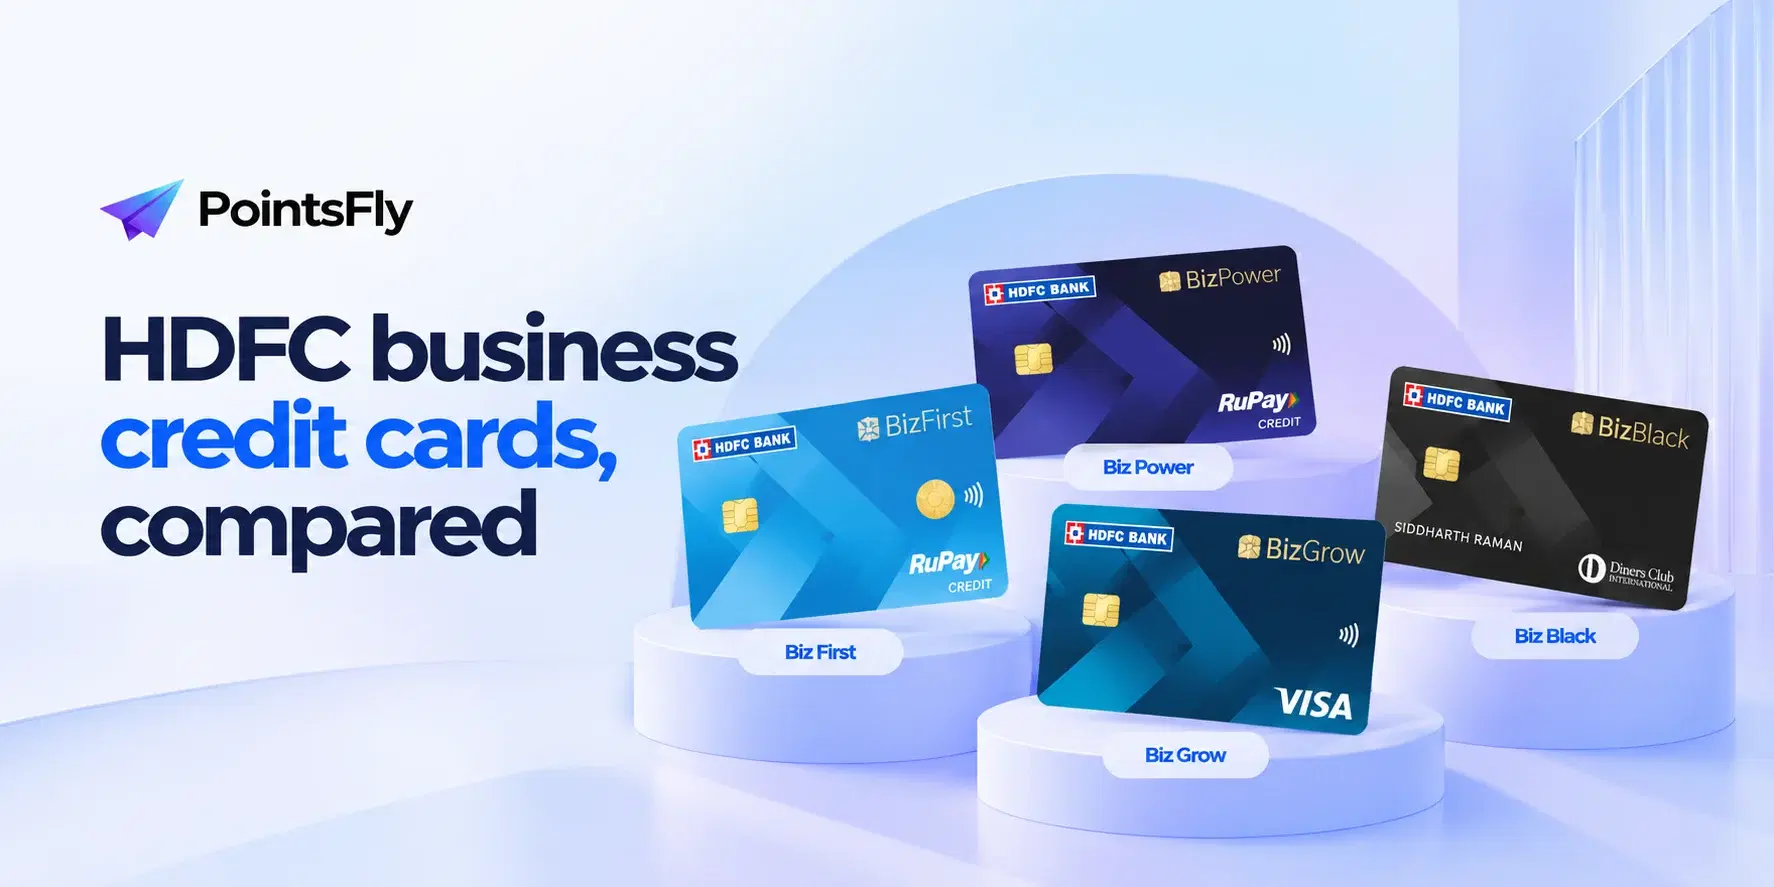
If you run a business or work for yourself, HDFC has four main cards for you: Biz First, Biz Grow, BizPower and Biz Black. On HDFC’s site, every HDFC business credit card looks pretty similar. They all promise interest-free days, CashPoints or Reward Points, and something for your GST payments.
Look closer, though, and they’re very different cards. One gives you about 0.1% back on everyday spends. Another can give you over 15% back on your GST and software bills. So we worked out what each one is actually worth in rupees, and which one fits the way your business spends.
 Quick Answer
Which HDFC business credit card is best?
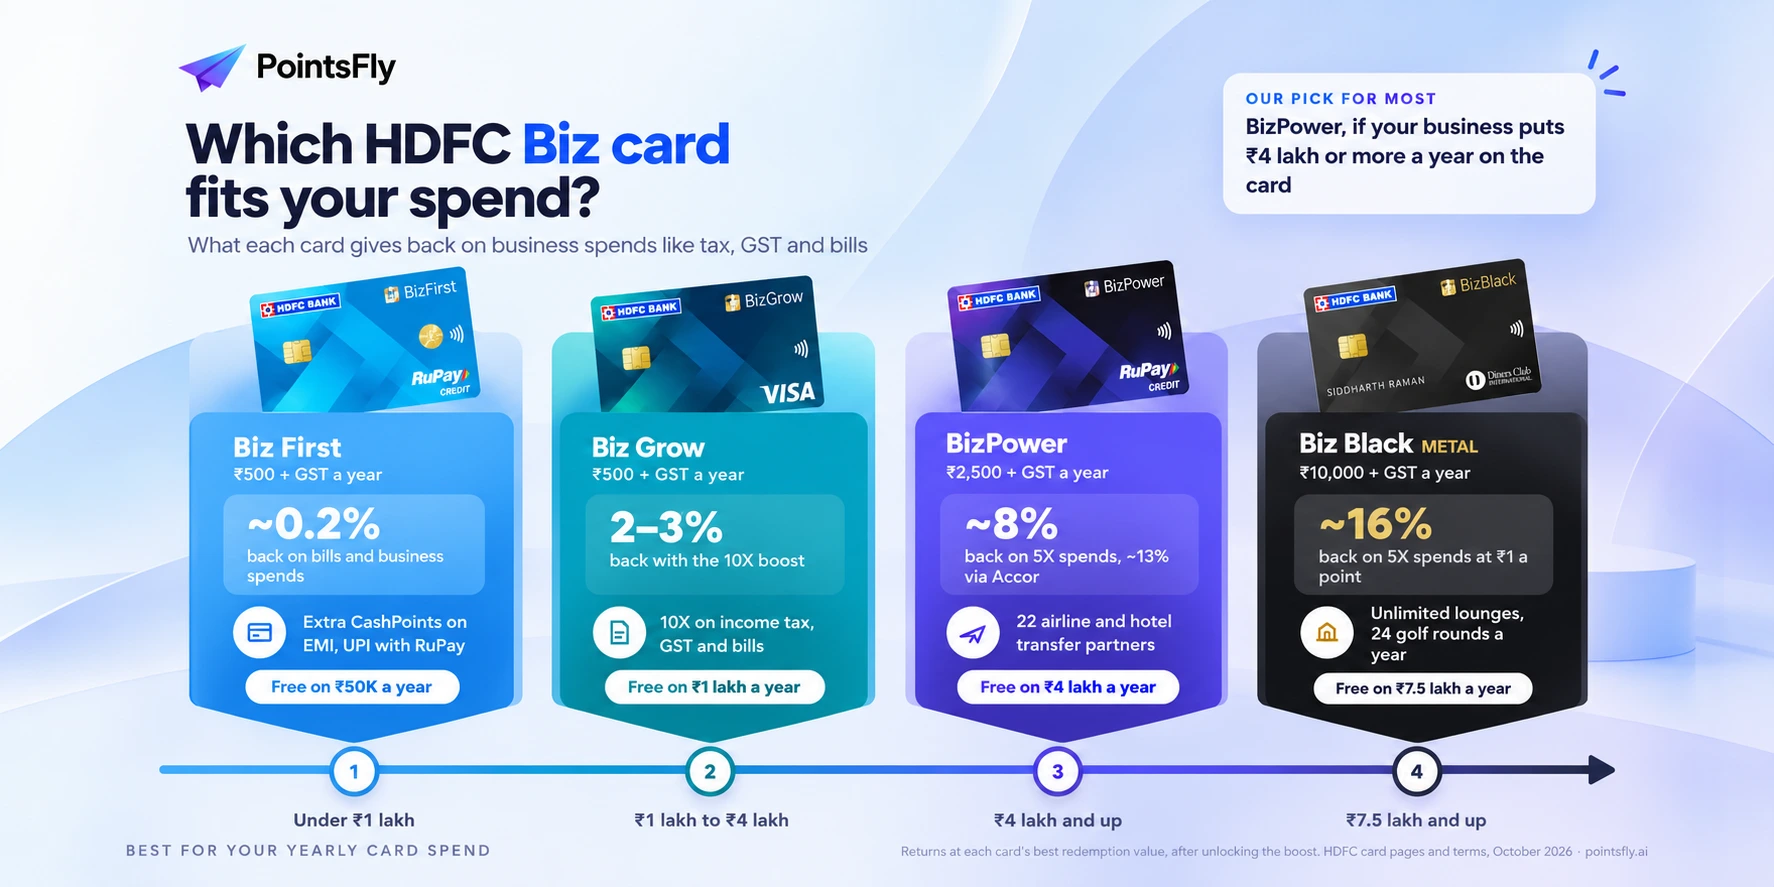
For most small businesses spending ₹4 lakh or more a year, HDFC BizPower (₹2,500) is the best HDFC business credit card. It earns 5X on tax, GST, ads and bills, and its points transfer to 22 airline and hotel partners. Pick Biz Black (₹10,000) if you spend ₹7.5 lakh or more a year and travel often, and Biz Grow if you want a low fee.
Key takeaways
 HDFC has four main business cards. Biz First and Biz Grow cost ₹500, BizPower ₹2,500 and Biz Black Metal ₹10,000, all plus GST.
 Only BizPower and Biz Black earn points you can send to airlines and hotels. Biz First and Biz Grow earn CashPoints, worth ₹0.10 to ₹0.30 each.
 Biz Grow, BizPower and Biz Black boost your tax and GST payments. Each has its own unlock spend and cap. Biz First earns only its base rate there.
 Lounge access is unlimited on Biz Black, conditional on BizPower and missing on Biz Grow and Biz First.
 Pick the card whose fee waiver you’ll hit easily. That’s ₹50,000, ₹1 lakh, ₹4 lakh or ₹7.5 lakh of spend a year.
Table of contents
- All four at a glance
- Fees and eligibility
- Rewards in rupees
- Tax and GST
- Lounges and travel
- Which card suits you
- Biz Black vs BizPower
- Biz Grow vs Biz First
- How to apply
- Let PointsFly do the tracking
- Cite this data
- FAQs
HDFC business credit cards at a glance (all four compared)
Here’s every HDFC Bank business credit card in the Biz range, side by side. CP means CashPoints and RP means Reward Points.
| Biz First | Biz Grow | BizPower | Biz Black Metal | |
|---|---|---|---|---|
| Annual fee | ₹500 + GST | ₹500 + GST | ₹2,500 + GST | ₹10,000 + GST |
| Fee waived on | ₹50,000 a year | ₹1 lakh a year | ₹4 lakh a year | ₹7.5 lakh a year |
| ITR needed | Above ₹6 lakh | Above ₹6 lakh or ₹12 lakh (HDFC’s pages differ) | Above ₹12 lakh | Above ₹45 lakh (an older page says ₹30 lakh) |
| Base earn | 1 CP per ₹100 | 2 CP per ₹200 | 5 RP per ₹200 | 5 RP per ₹150 |
| Business boost | 3 CP per ₹100 on EMI, 2 on bills | 10X | 5X | 5X |
| Point value (best use) | Up to ₹0.15 | Up to ₹0.30 | Up to ₹0.65, more via transfers | Up to ₹1 |
| Lounges | None | None | 2 domestic a quarter (conditional) + 6 international a year | Unlimited worldwide |
| Airline and hotel transfers | No | No | 22 partners | Yes, KrisFlyer at 1:1 |
| Forex markup | 3.5% | 3.5% | 2% | 2% |
All four give you up to 55 interest-free days. HDFC also has older and co-branded business cards, like Business Regalia, Business MoneyBack, Giga and Paytm Business. We’ve stuck to the four Biz cards here because they’re the ones HDFC is building its business range around.
Fees, fee waivers and eligibility
Annual fees and how to get them waived
On every card, the joining fee and the renewal fee are the same. You pay the first one, but you can get the renewal fee waived by spending enough in your card year. On Biz First, Biz Grow and BizPower, that first fee shows up about 120 days after you get the card.
The waiver is worth thinking about. If your business spends ₹5 lakh a year on the card, BizPower is free and Biz Black costs you ₹11,800 with GST.
Who can apply
All four are for self-employed Indian citizens aged 21 to 65. The real difference is your income tax return. Biz First needs an ITR above ₹6 lakh, BizPower above ₹12 lakh and Biz Black above ₹45 lakh.
Two of these aren’t clear-cut, because HDFC’s own pages disagree. Biz Grow’s product page says ₹6 lakh, while its eligibility page says ₹12 lakh. Biz Black’s product page says ₹45 lakh, but an older eligibility page still says ₹30 lakh. HDFC also checks your credit history and banking relationship, so meeting the ITR number doesn’t mean you’ll be approved.
You can apply with your ITR, GST returns, bank statements or merchant payment reports.
Other charges worth knowing
Forex markup is 3.5% on Biz First and Biz Grow, and 2% on BizPower and Biz Black. All four charge 1% on rent payments made through apps, and 1% on big fuel and utility bills over HDFC’s limits. Paying in rupees abroad (dynamic currency conversion) costs 1.75%.
HDFC business credit card benefits: rewards compared in rupees
This is where the four cards really split apart. A “point” isn’t worth the same on each card, so the only fair way to compare them is in rupees.
What a point is worth on each card
| Card | Statement cashback | Best use | Value at best use |
|---|---|---|---|
| Biz First | ₹0.10 per CP | SmartBuy, catalogue | Up to ₹0.15 |
| Biz Grow | ₹0.20 per CP | Business catalogue | Up to ₹0.30 |
| BizPower | ₹0.15 per RP | Business catalogue, or Accor and Avios transfers | ₹0.65, or about ₹1 to ₹2 |
| Biz Black | ₹0.30 per RP | SmartBuy flights and hotels | Up to ₹1 |
Here’s the catch with Biz First. HDFC calls it “1% CashPoints”, but a CashPoint is worth just ₹0.10 as cashback. So 1% CashPoints is really about 0.1% back in rupees, and “3% on EMI” is about 0.3%.
What you get back on everyday spends
On regular spends, like supplies, dining or a laptop, you get roughly:
- Biz First: 0.1% to 0.15%
- Biz Grow: 0.2% to 0.3%
- BizPower: about 1.6% in the business catalogue, and about 2.6% if you transfer to Accor
- Biz Black: about 3.3%, when you use your points for flights and hotels on SmartBuy
What you get back on business spends (the boost)
Each card earns more on what HDFC calls business essentials. These are bills paid through SmartPay or PayZapp, income tax and GST on the official portals, flights and hotels on MMT MyBiz through SmartBuy BizDeals, and software like Tally, Microsoft 365, AWS and Google Workspace through BizDeals. BizPower adds Google Ads and Reliance Digital, and Biz Grow adds DMart and ClearTax.
The boost comes with an unlock and a cap:
- Biz Grow (10X): Spend ₹10,000 in the cycle and you earn 20 CP per ₹200. That’s about 2% to 3% back. The boost stops at 1,500 CashPoints a cycle, worth ₹300 to ₹450.
- BizPower (5X): Spend ₹25,000 on things other than tax and GST, and you earn 25 RP per ₹200. That’s about 8% back in the catalogue and about 13% at Accor. Extra points stop at 7,500 a cycle.
- Biz Black (5X): Spend ₹50,000 in these categories in the cycle, and you earn 25 RP per ₹150. That’s about 16% back at ₹1 a point. Extra points stop at 7,500 a cycle.
Put another way, here’s roughly what ₹1 lakh of business-essential spend in a cycle earns you, once the boost is on. On Biz First, it’s ₹50 to ₹200. On Biz Grow, it’s under ₹750, because of the cap. On BizPower, it’s about ₹6,500 in the catalogue. On Biz Black, it’s close to ₹10,800.
Milestone benefits
- Biz First: 2,000 CP when you spend ₹75,000 in a quarter. That’s ₹200 to ₹300.
- Biz Grow: 2,000 CP when you spend ₹1 lakh in a quarter. That’s ₹400 to ₹600.
- BizPower: A ₹5,000 MakeMyTrip or Reliance Digital voucher when you spend ₹2.5 lakh in a quarter.
- Biz Black: A ₹5,000 flight or Taj voucher for every ₹5 lakh you spend in a calendar year, up to ₹20,000.
Want to see what your business card is really earning?
Try our free Reward Points Calculator and compare your cards before you transfer a single point.
Paying income tax and GST with an HDFC business card
All four cards let you pay income tax on the e-Filing portal and GST on the GST portal. What you earn on those payments is very different, though.
- Biz Grow: 10X on income tax and GST, inside the 1,500 CashPoint cycle cap.
- BizPower: 5X, but only after ₹25,000 of other spends in the cycle. Only your first 2 income tax and first 2 GST payments in each cycle earn points.
- Biz Black: 5X. Tax and GST count towards the ₹50,000 you need to unlock it.
- Biz First: Just the base 1 CP per ₹100, inside the 500 CashPoint monthly cap. There’s no boost.
Remember that the portals charge a fee of about 1% for card payments, plus GST. So the tax rewards only pay off on BizPower and Biz Black, and on Biz Grow up to its cap. Our guide on how to pay income tax and GST with a credit card has the steps and the full maths.
Lounge access and travel benefits
Biz Black gives you unlimited visits to over 1,000 Diners Club lounges in India and abroad, and your add-on cardholders get them too. The only catch is that you need to use the card at least once in the month before. It also comes with 24 free golf rounds a year. New cards set up from 15 September 2026 also get an Accor+ Explorer membership once you spend ₹1.5 lakh in 90 days.
BizPower gives you 2 domestic lounge visits a quarter, but only if you spent ₹75,000 in the previous quarter. You also get a MakeMyTrip zero-cancellation voucher each quarter on that same spend, and 6 international lounge visits a year through Priority Pass.
Biz Grow and Biz First don’t come with any lounge access.
All four cards get up to 4% off flights and hotels on MMT MyBiz through SmartBuy BizDeals, plus up to 40% off some business software.
Which HDFC business credit card should you get?
It mostly comes down to two things. How much does your business put on the card in a year, and what does it spend on?
Biz First: for new businesses and EMI or UPI spends
Biz First makes sense if you’re just starting out and spend less than ₹1 lakh a year. Its fee is waived at ₹50,000, and you can use the RuPay version on UPI. Just don’t pick it for rewards, because they’re small.
Biz Grow: a low fee with tax and GST rewards
Biz Grow fits if you spend ₹1 lakh to ₹4 lakh a year and pay GST by card, but don’t travel much. The 10X boost on tax, GST and bills is useful, as long as you remember the cap.
BizPower: the best all-rounder
BizPower is the one we’d pick for most businesses spending ₹4 lakh or more a year. If a lot of your money goes on GST, income tax, Google Ads or bills, the 5X adds up fast. Its points also transfer to 22 airline and hotel partners, with Accor at 2:1. See our full HDFC Biz Power credit card guide for more.
Biz Black: for big spenders who travel
Biz Black is for businesses spending ₹7.5 lakh or more a year that fly often. At that spend, the fee is waived, the lounges are unlimited and points are worth up to ₹1 each. You’ll need an ITR above ₹45 lakh to get it, though.
HDFC Biz Black vs BizPower
Most people end up choosing between these two. Here’s how they stack up where it counts.
| BizPower | Biz Black Metal | |
|---|---|---|
| Annual fee | ₹2,500 + GST | ₹10,000 + GST |
| Fee waived on | ₹4 lakh a year | ₹7.5 lakh a year |
| Base earn | 5 RP per ₹200 | 5 RP per ₹150 |
| Best point value | ₹0.65 (catalogue), about ₹1.05 at Accor | Up to ₹1 (SmartBuy flights and hotels) |
| Lounges | 2 domestic a quarter (conditional) + 6 international | Unlimited, worldwide |
| ITR needed | Above ₹12 lakh | Above ₹45 lakh |
So which one wins? If you’ll spend ₹7.5 lakh or more a year, Biz Black’s fee is waived and it earns more on almost everything. Below about ₹6 lakh, BizPower usually comes out ahead, because Biz Black’s fee eats most of its extra rewards. In between, it comes down to how much you’ll use the lounges.
BizPower also has one trick of its own. On Accor, it transfers at 2:1, the same as HDFC Infinia, so hotel stays work out almost as well as on Biz Black.
HDFC Biz Grow vs Biz First
Both cost ₹500 a year, so it really comes down to how you spend.
- Biz Grow wins if you pay GST, income tax or business bills by card. Its 10X boost and higher point value beat Biz First on almost everything.
- Biz First wins if most of your spends are on EMI or UPI. It earns 3 CP per ₹100 on EMI and works on UPI with the RuPay version. Its fee is also waived at a lower spend.
For most businesses, Biz Grow is the better ₹500 card.
How to apply for an HDFC business credit card
You can apply online on HDFC’s website or at a branch. Online, it takes four steps:
- Enter your phone number and date of birth or PAN.
- Confirm your details.
- Pick your card.
- Submit your application. HDFC may ask for documents or a video KYC.
If you already hold an HDFC card, you can also ask about an upgrade. Just know that welcome benefits often don’t apply to upgrades.
Let PointsFly do the tracking
Four cards, two kinds of points, different unlock spends and caps, and lounge access that depends on last quarter. Keeping track of all that every month is a job in itself.
PointsFly does it for you. It knows what your points are worth on every card you hold. When a big payment comes up, it shows you which card to use, and where to use the points afterwards.
Ready to see what your business card is really worth?
Start your free PointsFly trial and find the best way to use every point you have.
Download the PointsFly app
Track every card, see what your points are worth, and get the best flight and hotel deals for them. 7 days free.
Read next: our HDFC Biz Power credit card guide, the HDFC BizPower transfer partners ranked by value, and how to pay income tax and GST with a credit card.
Cite this data
Writing about HDFC business credit cards? Feel free to use our numbers.
Fees, earn rates, caps and point values come from HDFC Bank’s card pages, reward terms and Most Important Terms and Conditions (October 2026 version), checked on 30 October 2026. Accor values come from PointsFly’s guide to what Accor points are worth.
Something like this works: “PointsFly estimates HDFC BizPower gives back about 8% on business spends like GST and software, against about 0.1% on everyday spends with Biz First.”
All we ask is a link back. We update these numbers when HDFC changes its cards.
FAQs
About the author
 Vibhav Singh is the Founder & CEO of PointsFly and a credit card rewards strategist with 39K+ Instagram followers (@pointsflywithvibhav). He has personally booked 200+ flights on points and previously built XTEN-AV, an AI-powered SaaS platform now used in 130+ countries.