
Know Your Cards14 min read
Checked against American Express India’s card pages, October 2026.
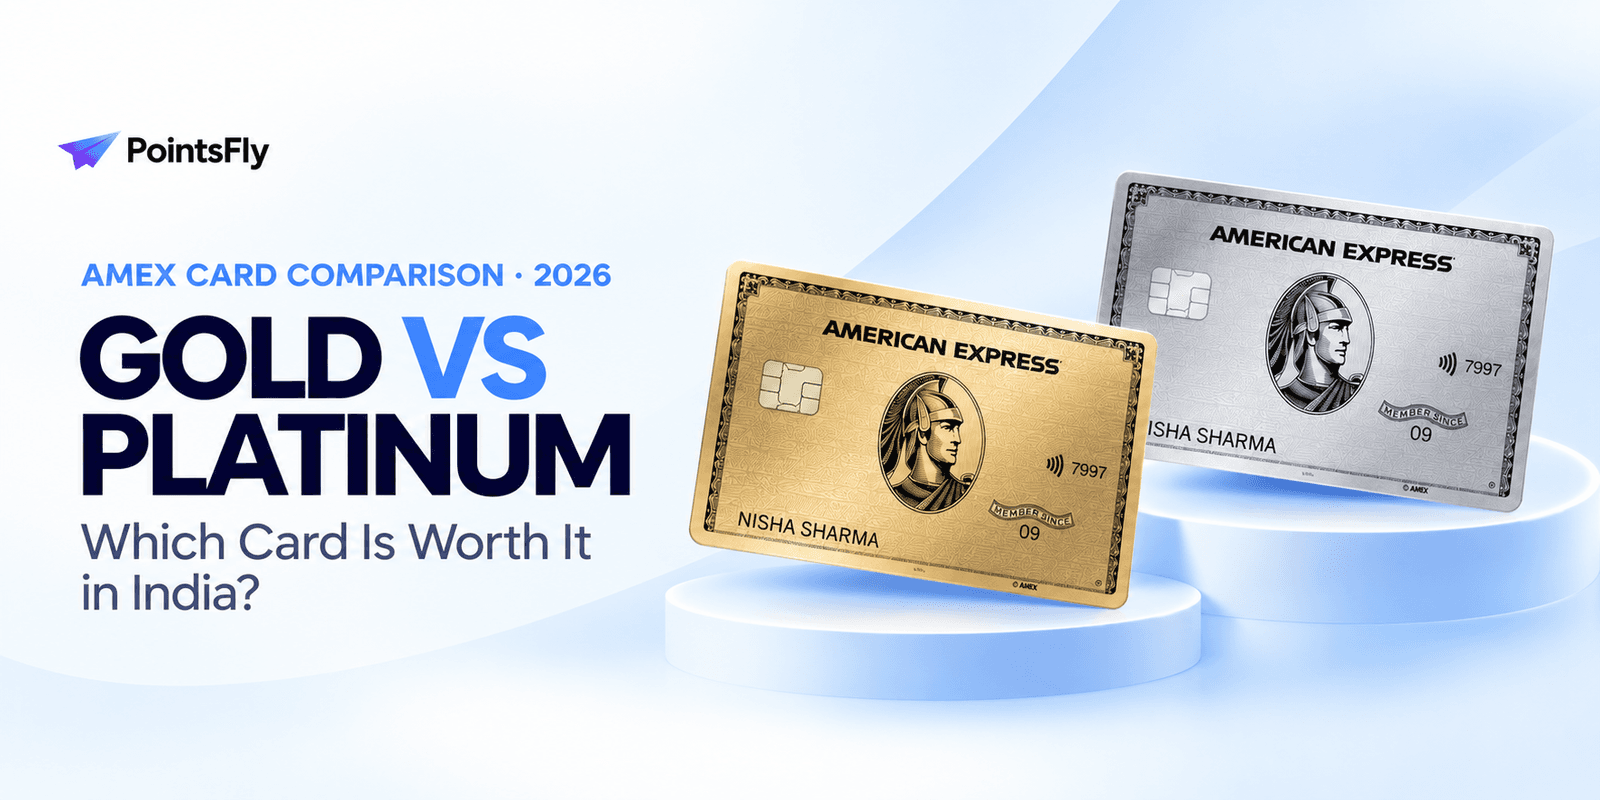
Search for Amex Gold vs Platinum and you’ll mostly find American pages, with dollar fees and perks you can’t use here. The Indian cards are quite different, so the advice doesn’t carry over.
Here in India, the two are closer than you’d think. They’re both charge cards and they earn the very same Membership Rewards points. But one will set you back ₹4,500 a year, and the other ₹66,000.
So which one gives you more back? We put the two side by side, ran the numbers at four spend levels, and found the point where the Platinum actually starts to pay off.
 Quick Answer
Amex Gold vs Platinum: which is better?
For most of us in India, it’s the Gold. You pay ₹4,500 a year, your utility bills earn points, and there’s a 1,000-point bonus waiting every month. Go for the Platinum only if you put ₹20 lakh or more on it in a year and you’ll really use the hotel status, the Fine Hotels + Resorts perks and the lounges abroad.
Key takeaways
 The fee gap is ₹72,570 a year. With GST, you’re looking at roughly ₹5,310 for Gold and ₹77,880 for Platinum.
 Up to ₹24 lakh a year, Gold keeps pace with Platinum on points. That monthly 1,000-point bonus is what closes the gap.
 Your electricity, gas and water bills earn on Gold. On Platinum they don’t, though fuel does.
 Platinum’s real edge is travel. Think elite status with seven hotel and travel programmes, lounges, and a renewal gift of up to ₹35,000 when you cross ₹20 lakh.
 Points stop pooling on 15 November 2026. Hold both? Then spend on the one you’ll redeem from.
Table of contents
- At a glance
- What’s the same
- Earning points
- What the extra fee buys
- The maths
- Which to pick
- Upgrading from Gold
- Where your value leaks
- Let PointsFly do the tracking
- Cite this data
- FAQs
Amex Gold vs Platinum at a glance
The main difference between the Amex Gold and Platinum is what you pay for. With Gold, you’re paying for points. With Platinum, you’re paying for travel benefits.
| Amex Gold Card | Amex Platinum Card | |
|---|---|---|
| Annual fee | ₹1,000 + GST in year one, then ₹4,500 + GST | ₹66,000 + GST every year |
| Welcome gift | 4,000 bonus points (₹10,000 spend in 90 days) | Vouchers worth up to ₹60,000 (₹50,000 spend in 2 months) |
| Everyday earn | 1 point per ₹50 | 1 point per ₹40 |
| Monthly bonus | 1,000 points for 6 spends of ₹1,000 | None |
| Utility bills | Earn points (up to 10,000 a month) | No points |
| Fuel | No points | 5 points per ₹100 (up to 5,000 a month) |
| Spends abroad | 1 point per ₹50 | 3 points per ₹40 |
| ShopWise | 5 points per ₹50 | 5 points per ₹40 |
| Renewal benefit | 5,000 points at your first renewal | Vouchers worth up to ₹35,000 at ₹20 lakh spend |
| Lounge access | Not included | 1,550+ lounges, Centurion included |
| Hotel status | None | Marriott Gold, Hilton Gold and five more |
| Minimum income | ₹6 lakh a year | ₹25 lakh a year (salaried) |
What’s the same on both cards
Quite a lot, which is why the fee gap feels so big.
Both are charge cards with no preset spending limit. You pay the full bill every month, and Amex approves each charge based on how you spend and pay. Both earn Membership Rewards points, so your points go to the same airline and hotel partners, like Singapore Airlines, Virgin Atlantic, Marriott and Hilton.
And right now, you can’t apply for either one. Amex has paused new card applications in India while it updates its systems.
Earning points: where each card wins
Everyday spending
The Platinum earns 1 point for every ₹40, and the Gold earns 1 point for every ₹50. That’s 2.5 points per ₹100 against 2 points per ₹100. On paper, Platinum wins by 25%.
Gold’s monthly bonus
This is the part most comparisons miss. Make six transactions of ₹1,000 or more in a calendar month on the Gold Card, and Amex adds 1,000 bonus points. Do that every month and it’s 12,000 extra points a year, which is enough to wipe out Platinum’s lead until you spend about ₹24 lakh a year.
Utilities and fuel
The Gold Card earns on electricity, gas and water bills, up to 10,000 points a month. The Platinum earns nothing on them. It’s the other way round with fuel: the Platinum earns 5 points per ₹100 (up to 5,000 points a month), while the Gold earns nothing on fuel.
Spending abroad
Here the Platinum pulls well ahead. It earns 3 points per ₹40 on any foreign currency spend, so that’s 7.5 points per ₹100. The Gold stays at its usual 2.
ShopWise and RewardXcelerator
Both earn 5X on ShopWise vouchers, so the Platinum gets 5 points per ₹40 and the Gold gets 5 per ₹50. We’ve covered the rates and limits in our ShopWise guide. Platinum holders also get RewardXcelerator till 31 January 2027. That’s 10X or 20X at places like Tata CLiQ Luxury, Dyson and Air India.
What the extra ₹72,570 gets you
The Platinum’s fee mostly pays for travel. Here’s what it adds on top of the Gold:
- Elite status with Marriott and Hilton (both Gold), plus Taj, Radisson, Accor, The Postcard Hotels and Hertz.
- Fine Hotels + Resorts stays, where breakfast for two, a 4pm checkout and a US$100 hotel credit come with the room.
- Lounges, and lots of them. Over 1,550 at 500+ airports, Centurion Lounges included. Just note that Priority Pass is free abroad but costs US$35 a visit in India.
- Bigger gifts. Up to ₹60,000 when you join, and up to ₹35,000 each year you cross ₹20 lakh.
- Cover and help on call. There’s ₹5 crore of air accident cover when you book the ticket on the card, and the Platinum Concierge picks up 24×7.
The Gold Card keeps things simple. There’s up to 20% off at partner restaurants and 5,000 points when you renew. Then there’s the Gold Collection, where 24,000 points become a ₹14,000 Taj voucher. No lounges, no hotel status.
The full list of Platinum benefits is on our Amex Platinum card guide.
The maths: when does Platinum pay off?
Let’s put real numbers on it. We’ve counted points at ₹1 each, which is what you’d get from a good airline transfer, and taken each card’s yearly fee off. The Gold figures assume you hit the monthly bonus every month.
| Yearly spend | Gold points | Gold value after fee | Platinum points | Platinum value after fee (incl. renewal gift) | Perks Platinum needs to catch up |
|---|---|---|---|---|---|
| ₹6 lakh | 24,000 | ₹18,690 | 15,000 | Minus ₹62,880 | ₹81,570 |
| ₹12 lakh | 36,000 | ₹30,690 | 30,000 | Minus ₹47,880 | ₹78,570 |
| ₹24 lakh | 60,000 | ₹54,690 | 60,000 | ₹17,120 | ₹37,570 |
| ₹36 lakh | 84,000 | ₹78,690 | 90,000 | ₹47,120 | ₹31,570 |
The last column is the one to look at. At ₹24 lakh a year, both cards earn the same 60,000 points. The Platinum then needs about ₹37,500 of hotel and travel perks a year, perks you’d actually use, to come out level with the Gold.
That’s very doable if you take a few trips abroad and book FHR hotels. It’s much harder if most of your travel is within India. And these numbers leave out utilities (only Gold earns) and foreign spends (Platinum earns 3X), so check which side your own spending leans to.
Person A vs Person B
Person A spends ₹1.5 lakh a month, mostly in India, and travels abroad once a year. On the Gold Card, that’s 48,000 points a year for a ₹5,310 fee. The Platinum would earn 45,000 points and miss the renewal gift, since ₹18 lakh doesn’t reach ₹20 lakh. For Person A, Gold is clearly the better deal.
Person B spends ₹3 lakh a month, flies abroad four times a year and books three FHR stays. The Platinum earns them 90,000 points plus the renewal gift, and three US$100 property credits alone cover most of the ₹31,570 gap. Add breakfasts, upgrades, Marriott Gold and lounge visits, and the Platinum comes out ahead.
Same points programme, two very different answers. It all comes down to how you spend and how often you fly.
Not sure what your Amex points are actually worth?
Try out our free Reward Points Calculator and see what your Membership Rewards points are really worth before you redeem them.
So, which one should you pick?
The Amex Gold Card is the better pick for most people in India, because it gives you nearly the same points for a fraction of the fee. The Platinum is worth it once your spending and travel are high enough to use what it adds.
Pick Gold if…
- You spend under ₹20 lakh a year.
- You pay big utility bills and want points on them.
- You make at least six spends of ₹1,000 every month, so you collect the monthly bonus.
- Most of your travel is in India, or you don’t use airport lounges much.
Pick Platinum if…
- You spend ₹20 lakh or more a year, so the renewal gift comes back to you.
- You fly abroad a few times a year and spend in foreign currency.
- You stay at Marriott, Hilton, Taj or FHR hotels and want the status and perks.
- You’d rather send points to airlines than redeem them for vouchers.
Upgrading from Gold to Platinum
If you hold the Gold Card, Platinum upgrade offers usually show up in your Amex account. The bonus points on these offers vary from person to person, so read the terms before you say yes.
One thing to keep in mind before you switch: 15 November. After that date your points stay on whichever card earned them, and there’s no moving them across. Planning to keep both? Pick the card you’ll redeem from and put most of your spending there.
Thinking about whether the Platinum will pay for itself long term? Our Amex Platinum 2026 breakdown runs the full numbers for existing cardholders.
Where your value quietly leaks
- Missing one of the six monthly spends on Gold. Five transactions don’t earn the bonus, so you lose 1,000 points that month. From 15 November, Amex counts them by posting date, so leave some room at the end of the month.
- Redeeming Gold points for Amazon vouchers. On the Gold Collection, that works out to about ₹0.33 a point. The same points can be worth ₹1 or more as airline miles.
- Putting fuel on the Gold Card. It earns nothing there, so use another card for fuel.
- Priority Pass in India on the Platinum. Each visit costs US$35. At Indian airports, use Amex’s domestic lounge partners instead.
- Points stuck on the wrong card. After 15 November, points on your Gold Card can’t move to your Platinum, or the other way round.
Let PointsFly do the tracking
Hitting six spends a month, tracking ₹20 lakh for the renewal gift and remembering which card holds which points is a lot to keep in your head. Most people just pay and hope it works out.
PointsFly keeps track of it for you. It shows you which card earns the most on each purchase, and when it’s time to redeem, it finds the transfer or hotel stay that gets you the most for your points.
Ready to see what your Amex points are worth?
Start your free PointsFly trial and see what your Membership Rewards points can really do.
Download the PointsFly app
Track every card, see what your points are worth, and get the best flight and hotel deals for them. 7 days free.
Read next: what Marriott Bonvoy points are worth, whether Infinia or Diners Black earns more, and a walkthrough of how to transfer credit card points to airlines and hotels.
Cite this data
Comparing the Amex Gold and Platinum? Feel free to use our numbers.
The card details come from American Express India’s Gold Card and Platinum Card pages, read in October 2026. The maths uses 1 point per ₹50 plus 12,000 bonus points a year for the Gold, 1 point per ₹40 for the Platinum, fees with 18% GST, and points valued at ₹1 (airline transfers).
Something like this works: “PointsFly estimates that the Amex Gold Card earns as many Membership Rewards points as the Amex Platinum up to ₹24 lakh of spending a year, for about ₹72,570 less in fees.”
All we ask is a link back. We update these numbers whenever Amex changes either card.
FAQs
About the author
 Vibhav Singh is the Founder & CEO of PointsFly and a credit card rewards strategist with 39K+ Instagram followers (@pointsflywithvibhav). He has personally booked 200+ flights on points and previously built XTEN-AV, an AI-powered SaaS platform now used in 130+ countries.