Fees, EDGE earn rates and all 24 transfer partners, plus what a point is really worth after the 2026 devaluation and who should still get this card.
| Joining fee | ₹12,500 + GST |
| Annual fee | ₹12,500 + GST |
| Fee waiver | ₹25 lakh / year |
| Base earn | 12 EDGE per ₹200 |
| Top earn | 60 EDGE per ₹200 |
Card overview
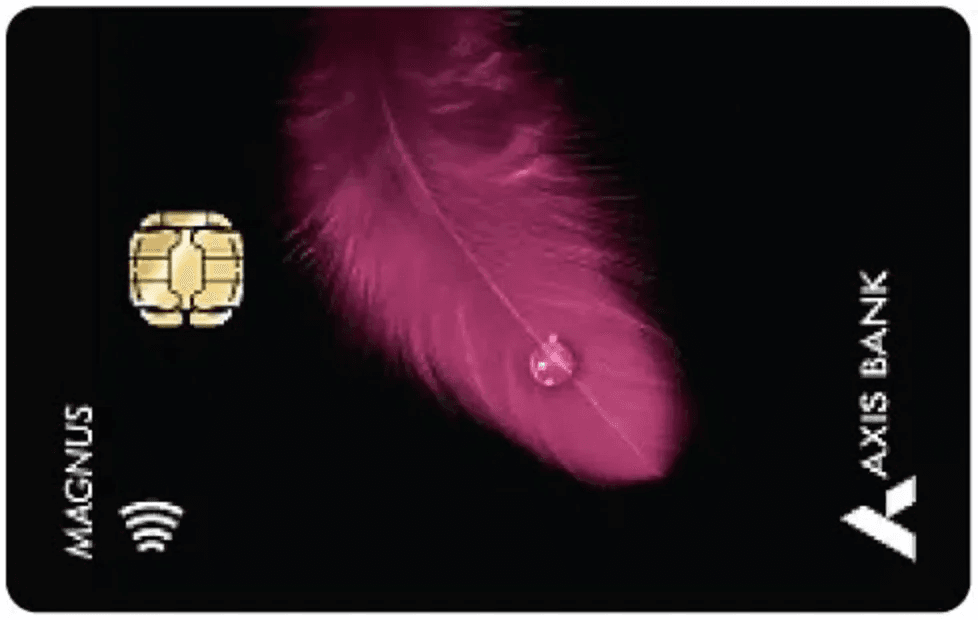
Axis Bank’s flagship travel card, built for people spending well above ₹1.5 lakh a month who’d rather turn that spend into flights and hotel stays than statement credit. Twenty-four airline and hotel transfer partners, the widest roster on any Indian card at this fee, plus unlimited international lounge access for the primary cardholder.
EDGE point value at a glance
The gap between the easy route and the good one is the whole card.
2 miles per 5 points
Transfer rate on 19 of 24 partners
₹0.20–₹0.25
Catalogue redemption
On ₹1.5 lakh of Travel EDGE spend, that’s the difference between a ₹10,000 voucher and miles worth two to three times more.
Where you earn, and where you don’t
Where you earn most
60 EDGE per ₹200
Bookings through the Travel EDGE portal. Capped at ₹2 lakh a month. A genuine 5x over the base rate.
Everyday rates
12 EDGE per ₹200 on spend up to ₹1.5 lakh a month.
35 EDGE per ₹200 on the portion above ₹1.5 lakh. Apple Pay holds the same rate.
Earns nothing
- Fuel
- Wallet loads
- EMI conversions
- Insurance
- Utilities
- Government payments
- Gold and jewellery
- Cash withdrawals
Key takeaways
- Twenty-four transfer partners, nineteen of them at the better 5 points : 2 miles rate. That roster is the reason to hold this card.
- The ₹12,500 fee waives only at ₹25 lakh of annual spend, a bar Axis raised from ₹15 lakh in September 2023. Most holders will pay it.
- Your first year is effectively free. The welcome voucher is worth ₹12,500, which is exactly the joining fee.
- Transfers are capped at 5,00,000 EDGE points per Customer ID per year. For heavy Travel EDGE spenders that cap, not the earn rate, is the real ceiling.
- Unlimited international lounge access for the primary cardholder. Domestic access needs ₹50,000 spent in the previous three months.
What’s in this guide
Axis Magnus credit card fees and charges
The Axis Magnus credit card has a joining fee of ₹12,500 plus GST and an annual fee of ₹12,500 plus GST, waived if you spend ₹25 lakh in the preceding year.
That waiver number deserves a second look. ₹25 lakh a year works out to just over ₹2 lakh a month, every month. Most people who hold this card will pay the fee. Plan on paying it, and judge the card on whether the benefits clear ₹12,500 of real value, not on whether you might scrape past the waiver.
The good news is that the welcome voucher covers the first year on its own. New cardholders pick one voucher worth ₹12,500 from Luxe, The Postcard Hotels or Yatra. Year one is effectively free. Year two is where the maths starts mattering.
| Charge | What you pay |
|---|---|
| Joining fee | ₹12,500 + GST |
| Annual fee | ₹12,500 + GST |
| Annual fee waiver | Spend ₹25 lakh in the preceding year |
| Welcome benefit | ₹12,500 voucher from Luxe, Postcard Hotels or Yatra |
| Foreign currency markup | 2% |
| Cash withdrawal fee | Nil, but interest applies from day one |
| Fuel surcharge waiver | 1% on transactions of ₹400 to ₹4,000, capped at ₹400 a month |
A note on that cash withdrawal line, because it reads better than it is. No withdrawal fee is genuinely unusual. But finance charges start the moment the cash leaves the ATM, with no interest-free period. Free fee, expensive money.
The 2% forex markup is the quietly useful one. Most Indian cards sit at 3.5%. On ₹5 lakh of overseas spend in a year, that difference is ₹7,500, more than half the annual fee, recovered without earning a single point.
How you earn EDGE points on Axis Magnus
Axis Magnus earns 12 EDGE points per ₹200 on regular spends, 35 points per ₹200 on monthly retail spend above ₹1.5 lakh, and 60 points per ₹200 on bookings made through the Travel EDGE portal.
| Where you spend | What you earn | Equivalent |
|---|---|---|
| Regular eligible spends | 12 EDGE points per ₹200 | 6 points per ₹100 |
| Monthly retail above ₹1.5 lakh | 35 EDGE points per ₹200 | 17.5 points per ₹100 |
| Travel EDGE portal | 60 EDGE points per ₹200 | 30 points per ₹100 |
Travel EDGE is the headline. 60 points per ₹200 is five times the base rate. The cap sits at ₹2 lakh of Travel EDGE spend a month, which most people never come close to. But book that same flight on MakeMyTrip instead and you’re back down to 12 per ₹200. Same flight, same money, a fifth of the points.
The ₹1.5 lakh threshold trips people up constantly. It isn’t a switch that lifts your whole month to 35. Only what you spend above ₹1.5 lakh earns at the higher rate. So: spend ₹2 lakh, and your first ₹1.5 lakh earns at 12 while the last ₹50,000 earns at 35. Nearly everyone assumes it works the other way round.
When the points actually arrive
Base points land in roughly 15 days. Accelerated points take around 45. If you booked a big Travel EDGE trip and the points haven’t shown up, you are probably not missing them. You are waiting.
What earns you nothing
This list is longer than most premium cards, and it’s worth reading properly before you plan around the card.
- Wallet reloads and wallet payments
- EMI conversions
- Fuel
- Insurance premiums
- Gold and jewellery
- Utilities
- Government payments
- Cash withdrawals
- Anything refunded, reversed or cancelled
Utilities and insurance being excluded matters more than people expect. Those are exactly the large, predictable payments that would otherwise push you past the ₹1.5 lakh monthly threshold.
What your EDGE points are actually worth
EDGE points are worth roughly ₹0.20 to ₹0.25 each through the Axis catalogue, and 2x to 4x more when transferred to an airline or hotel partner.
This is the part that decides whether Magnus is a good card or an expensive one, and it has almost nothing to do with the earn rate.
Here’s the arithmetic. Say you book ₹1,50,000 of travel through Travel EDGE in a month. At 60 points per ₹200, that’s 45,000 EDGE points.
Redeem through the catalogue at ₹0.22 a point and you get about ₹9,900 in vouchers. Convenient. Fine. Nothing to complain about.
Transfer those same 45,000 points at the standard 5:2 ratio and you get 18,000 partner miles. On the right route, such as a one-way business class seat to Southeast Asia, 18,000 miles can be worth ₹40,000 or more in cash fares.
Same spend. Same points. 4x the value.
You can run the same maths on your own spend with our reward points calculator.
We say this a lot and we’ll say it again here: cashback and vouchers feel like the safe choice, and they are the most expensive thing you can do with a transferable point. The entire reason to pay ₹12,500 for this card is the transfer partner list. If you’re going to redeem for vouchers, a 2% cashback card will serve you better and cost you nothing.
Axis Magnus transfer partners
Axis Magnus transfers to 24 airline and hotel partners, 19 at 5 EDGE points to 2 partner miles and 5 at 5 to 1, with an annual cap of 5,00,000 points per Customer ID.
That roster is the widest available on an Indian credit card at this fee, and it’s the single strongest argument for holding Magnus.
Airlines at 5:2 (the good rate)
| Airline | Programme |
|---|---|
| Singapore Airlines | KrisFlyer |
| Air France-KLM | Flying Blue |
| United Airlines | MileagePlus |
| Air Canada | Aeroplan |
| Etihad Airways | Etihad Guest |
| Turkish Airlines | Miles&Smiles |
| Japan Airlines | JAL Mileage Bank |
| Thai Airways | Royal Orchid Plus |
| Qantas Airways | Qantas Frequent Flyer |
| Ethiopian Airlines | ShebaMiles |
| Air India | Maharaja Club |
| AirAsia | AirAsia Rewards |
| SpiceJet | SpiceClub |
Hotels at 5:2
| Hotel group | Programme |
|---|---|
| IHG Hotels & Resorts | IHG One Rewards |
| ITC Hotels | Club ITC |
| Wyndham Hotels | Wyndham Rewards |
| Radisson Hotels | Radisson Rewards |
| The Postcard Hotel | Sunshine Club |
| Orchid Hotels | Orchid Rewards |
Airlines at 5:1 (check before you move)
| Airline | Programme |
|---|---|
| British Airways | Executive Club (Avios) |
| Qatar Airways | Privilege Club |
| IndiGo | BlueChip |
| Finnair | Finnair Plus |
| Vietnam Airlines | Lotusmiles |
Five partners give you half the miles for the same points. British Airways and Qatar are genuinely useful programmes, so this isn’t a reason to avoid them. Just know you’re paying double before you hit transfer.
The cap most people find out about too late
Transfers are limited to 5,00,000 EDGE points per Customer ID per year, split as up to 1,00,000 points to Group A partners and up to 4,00,000 to Group B.
If you’re spending enough to max out Travel EDGE every month, that cap, not the earn rate, is what limits your returns. Worth knowing in January rather than November.
Axis Magnus credit card benefits
The main Axis Magnus benefits are unlimited international lounge access for the primary cardholder, 24 airline and hotel transfer partners, a 5x earn rate on Travel EDGE bookings, and a 2% foreign currency markup.
Beyond the points, there’s a reasonable spread of travel and lifestyle extras:
- Dining Delights: discounts at over 4,000 restaurants across India
- Credit shield: cover up to ₹5 lakh
- Purchase protection: up to ₹2 lakh on eligible purchases
- Baggage and document protection: up to USD 500 for lost or delayed baggage and lost personal documents
Insurance benefits on premium cards are usually worth less than the headline numbers suggest, and these come with the usual exclusions and claim conditions. Treat them as a backstop, not a reason to apply.
Axis Magnus lounge access
Axis Magnus gives the primary cardholder unlimited complimentary international lounge visits through Priority Pass, plus 4 complimentary international guest visits a year. Domestic lounge access is unlimited at select Indian airports, but requires ₹50,000 of eligible spend in the previous three months.
Unlimited international access is rare and it is the benefit most Magnus holders actually use. If you fly abroad three or four times a year with a companion, the guest visits alone are worth a few thousand rupees.
One detail for new cardholders: the ₹50,000 domestic spend requirement is waived for your first three months. After that it’s assessed on a rolling previous-three-month basis, so a quiet quarter can cost you domestic access in the next one.
What changed in the 2026 devaluation
Axis has reduced the value of this card three times since 2023: in September 2023, April 2024, and most recently on 28 August 2026. The fee waiver threshold went from ₹15 lakh to ₹25 lakh, the forex markup rose from 1.5% to 2%, and the exclusions list grew.
Everything on this page already reflects the current rules. If you want the full story on what each round took away, and whether the card still earns its fee afterwards, we’ve written that up separately: Axis Magnus devaluation 2026: what changed and what it costs you.
Axis Magnus credit card eligibility
Axis Magnus requires a minimum annual income of ₹24 lakh and is available to salaried and self-employed applicants aged 18 to 70.
| Requirement | Criterion |
|---|---|
| Minimum age | 18 years |
| Maximum age | 70 years |
| Minimum annual income | ₹24 lakh |
| Employment type | Salaried or self-employed |
| Credit score | No published minimum, subject to Axis Bank’s assessment |
Axis doesn’t publish a credit score cut-off for Magnus, but on a card at this income bracket, approval tends to go to applicants with a clean repayment history and limited existing obligations.
Should you get it?
Magnus works if you spend more than ₹1.5 lakh a month, book travel through Travel EDGE, and actually transfer your points to airline partners. Tick those three and the fee is comfortably covered.
It works badly if any one of them is missing. Spend less than ₹1.5 lakh and you never see the better rate. Book travel elsewhere and you lose the 5x. Redeem through the catalogue and you give away three quarters of the card’s value, at which point you’re paying ₹12,500 a year for lounge access you could get cheaper.
Your EDGE points are worth up to 4x more as miles
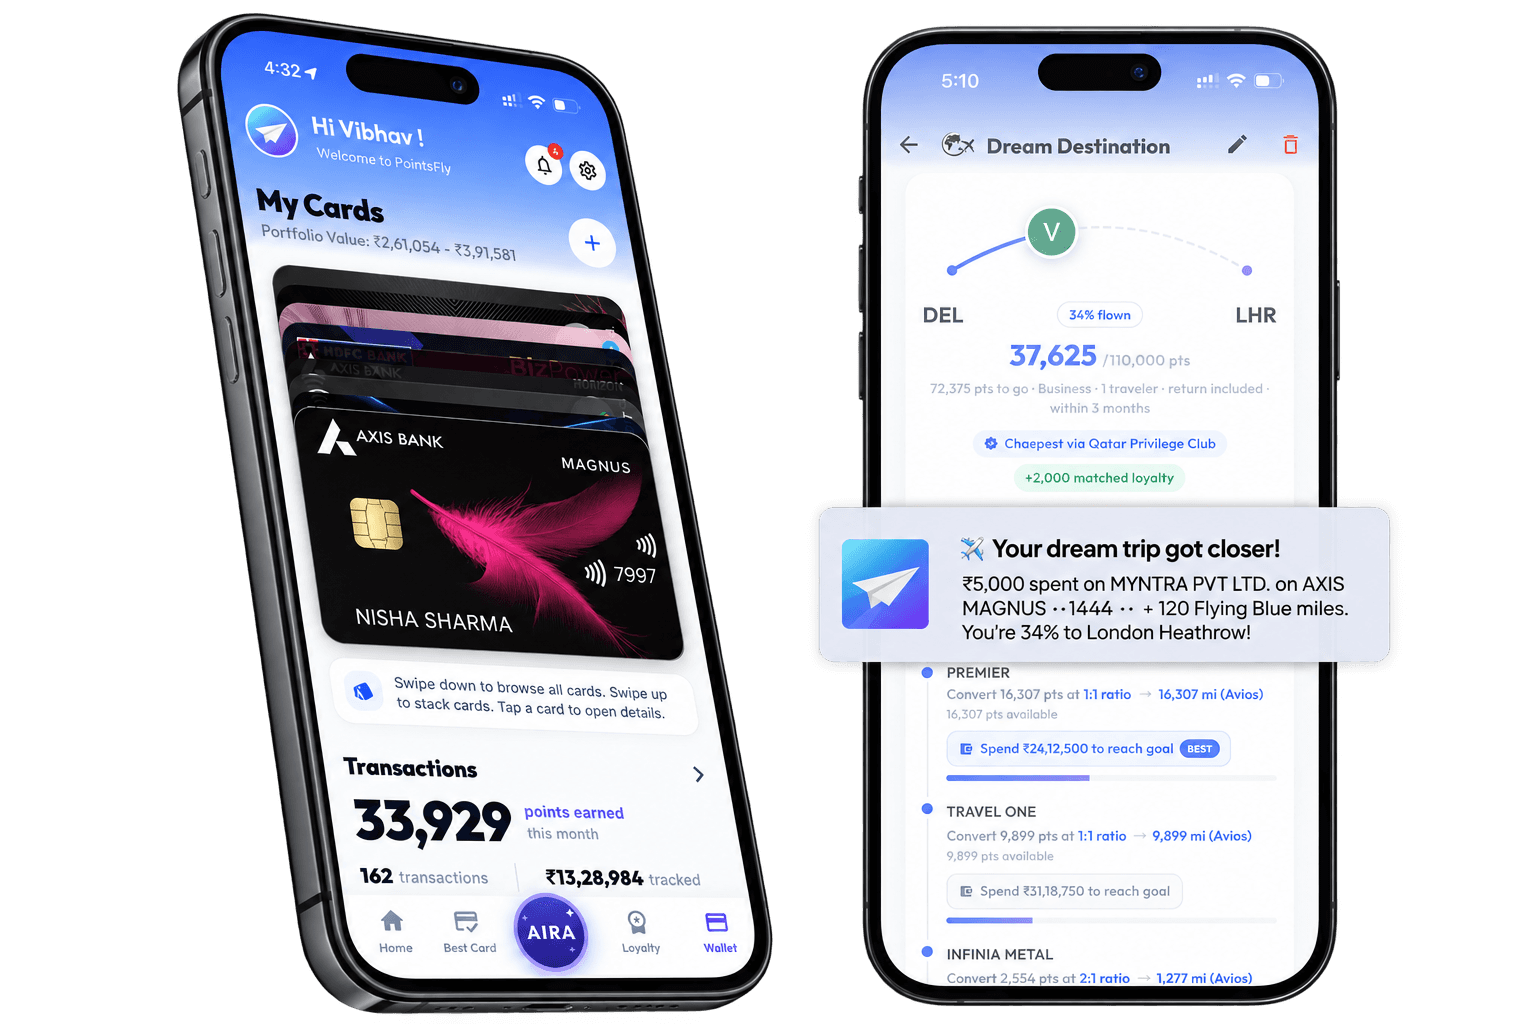
Let PointsFly show you which transfer is worth making, and turn those points into flights and hotel stays.
Card terms change often. This page reflects Axis Bank’s published terms as of 7 October 2026, including the revision effective 28 August 2026. Confirm current terms with Axis Bank before applying.
PointsFly may earn a commission if you apply for this card through the link on this page. It does not change what we write, the figures above, or what the card costs you.